Follow the money: how California funds public transit
 10.25.26 // Who pays for the bus anyway? Where do my gas taxes go? Why can’t fares alone fund transit?
 Grey Crawford, Contributing Writer
Public transit is extremely important for a developing city. But when a transit agency runs out of money, the effects are immediate and visible: routes are cut, service becomes less frequent, and riders who depend on transit are left stranded. Transit agencies across the nation are nearing this boiling point, often known as a ‘fiscal cliff.’
To understand how we got here, it’s important to consider transit’s entire funding picture and its challenges. Public transit in California does not fund itself. Rather, it is primarily funded by the government as a public service. But as public transit agencies face structural deficits, it’s important to understand exactly how transit agencies currently get their funding, and challenges associated with current funding, to understand why they need more. How does transit in California get its funding, exactly?
This article will summarize the most important sources of funding for public transit. It is important to note that this is not an exhaustive list. It aims to note the trade-offs for the most important sources of funding and argue that transit agencies need a balanced budget. Finally, we’ll see how these examples apply to San Diego’s public transit to understand why it faces a “fiscal cliff” and what must be done to avoid service cuts.
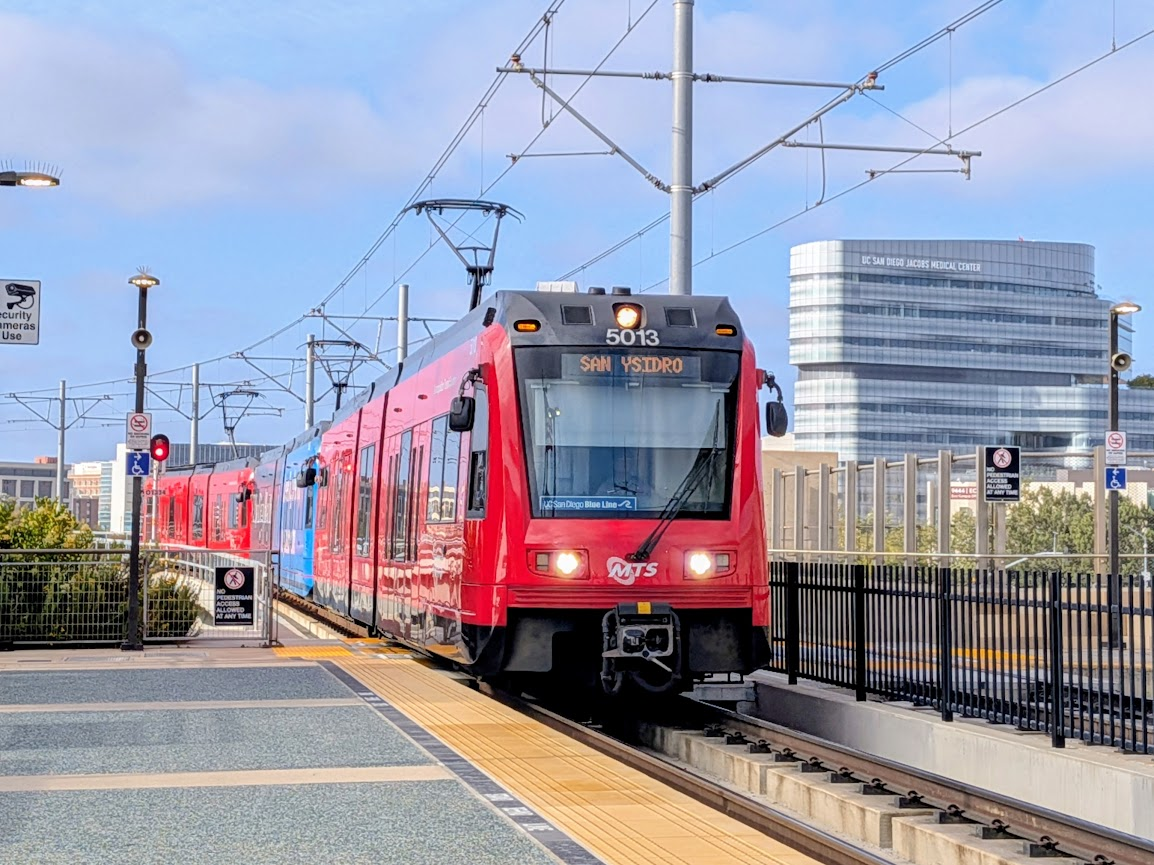 Photo by Grey Crawford / BuildSD
Federal Formula Funds / Mass Transit Account
The federal government funds transit through the Mass Transit Account, which comes from the federal gas tax and is made up of several kinds of grants called Formula Funds.
The most important formula fund for urban transit agencies is the Urbanized Area Formula Funding (5307) program. The 5307 program provides federal funding for transit capital and operating assistance in an Urbanized Area (UZA). ‘Urbanized Areas’ are designated by the Census Bureau and defined as an area that has a population of 50,000 or more. Section 5307 funds are apportioned by formula based on population, low-income population, and population density. For urbanized areas of 200,000 or more, the formula also includes transit service factors, such as vehicle revenue miles, route miles, passenger miles, and operating costs.
Urbanized Area Formula Grants funds can be spent on certain eligible activities, which include planning and engineering for transit projects, as well as capital investments such as replacement, overhaul and rebuilding of buses, or fixed guideway systems including rolling stock, station infrastructure, and tracks and signals. Section 5307 funds can also be used for operating expenses, but only in urbanized areas with populations under 200,000. Section 5307 funds are only one fund the federal government allocates to transit agencies. Some of these other funds include (but are not limited to):
- Rural Area Formula Program (section 5311) - Capital, planning, and operating assistance in rural areas with populations of less than 50,000.
- State of Good Repair Grants (section 5337) - Capital assistance for maintenance, replacement, and rehabilitation projects for high-intensity fixed guideway and motorbus to help maintain assets in a state of good repair in urbanized areas.
- Bus and Bus Facilities Program (section 5339) - Funding to purchase buses and related equipment and to construct bus-related facilities.
- Small Transit Intensive Cities (STIC) - Grants to small urban transit providers to enhance their efficiency and capacity, specifically for communities with populations between 50,000 and 200,000.
Money for formula programs comes from the Mass Transit Account (MTA). The MTA is part of the federal government’s Highway Trust Fund, funded by a dedicated piece of federal excise taxes on gasoline and diesel (2.86 cents per gallon).1
The distribution of the Mass Transit Account is based on surface transportation provisions decided by Congress. Most recently, these authorizations were made by the Infrastructure Investment and Jobs Act (IIJA, 2021). The IIJA expires in 2026. Congress usually does not pass a renewal right away, instead, it passes continuing authorizations until it does. The next surface transportation legislation, which is currently proposed as the BUILD America 250 Act (2026), will likely bring some change to 5307 formula funds and other surface transportation programs. As of October 2026, Congress has passed a partial renewal of the IIJA through December 11th, 2026 while the BUILD America 250 Act is negotiated in Congress.
Federal formula funds also see structural challenges as increased fuel efficiency and EV adoption erode gas tax revenue over time. This has led to a structural deficit for the Highway Trust Fund and the MTA as fuel tax revenue falls short of authorized spending. So far, periodic general fund transfers have been needed to keep the Highway Trust Fund solvent. The general fund is primarily made up of federal income taxes, but it is also financed with deficit spending. In the absence of reform to the trust fund, the federal government will need to continue borrowing money to fund transit, or transit agencies will see less transit funding from the MTA.
Most transit agencies apply for federal formula funds, but there are some exceptions. Federal funds carry with them requirements such as compliance with Title VI of the Civil Rights Act and Buy America laws, as well as drug and alcohol testing and reporting to the National Transit Database. These require administrative overhead which could be burdensome for smaller operators in particular. However, declining to apply for these funds means they are forgoing funding their communities have already contributed to by paying federal gas taxes which fund the Mass Transit Account. That money is distributed to other regions instead. Federal funds are generally worth their compliance cost for the sheer volume of capital and operating funds they unlock.
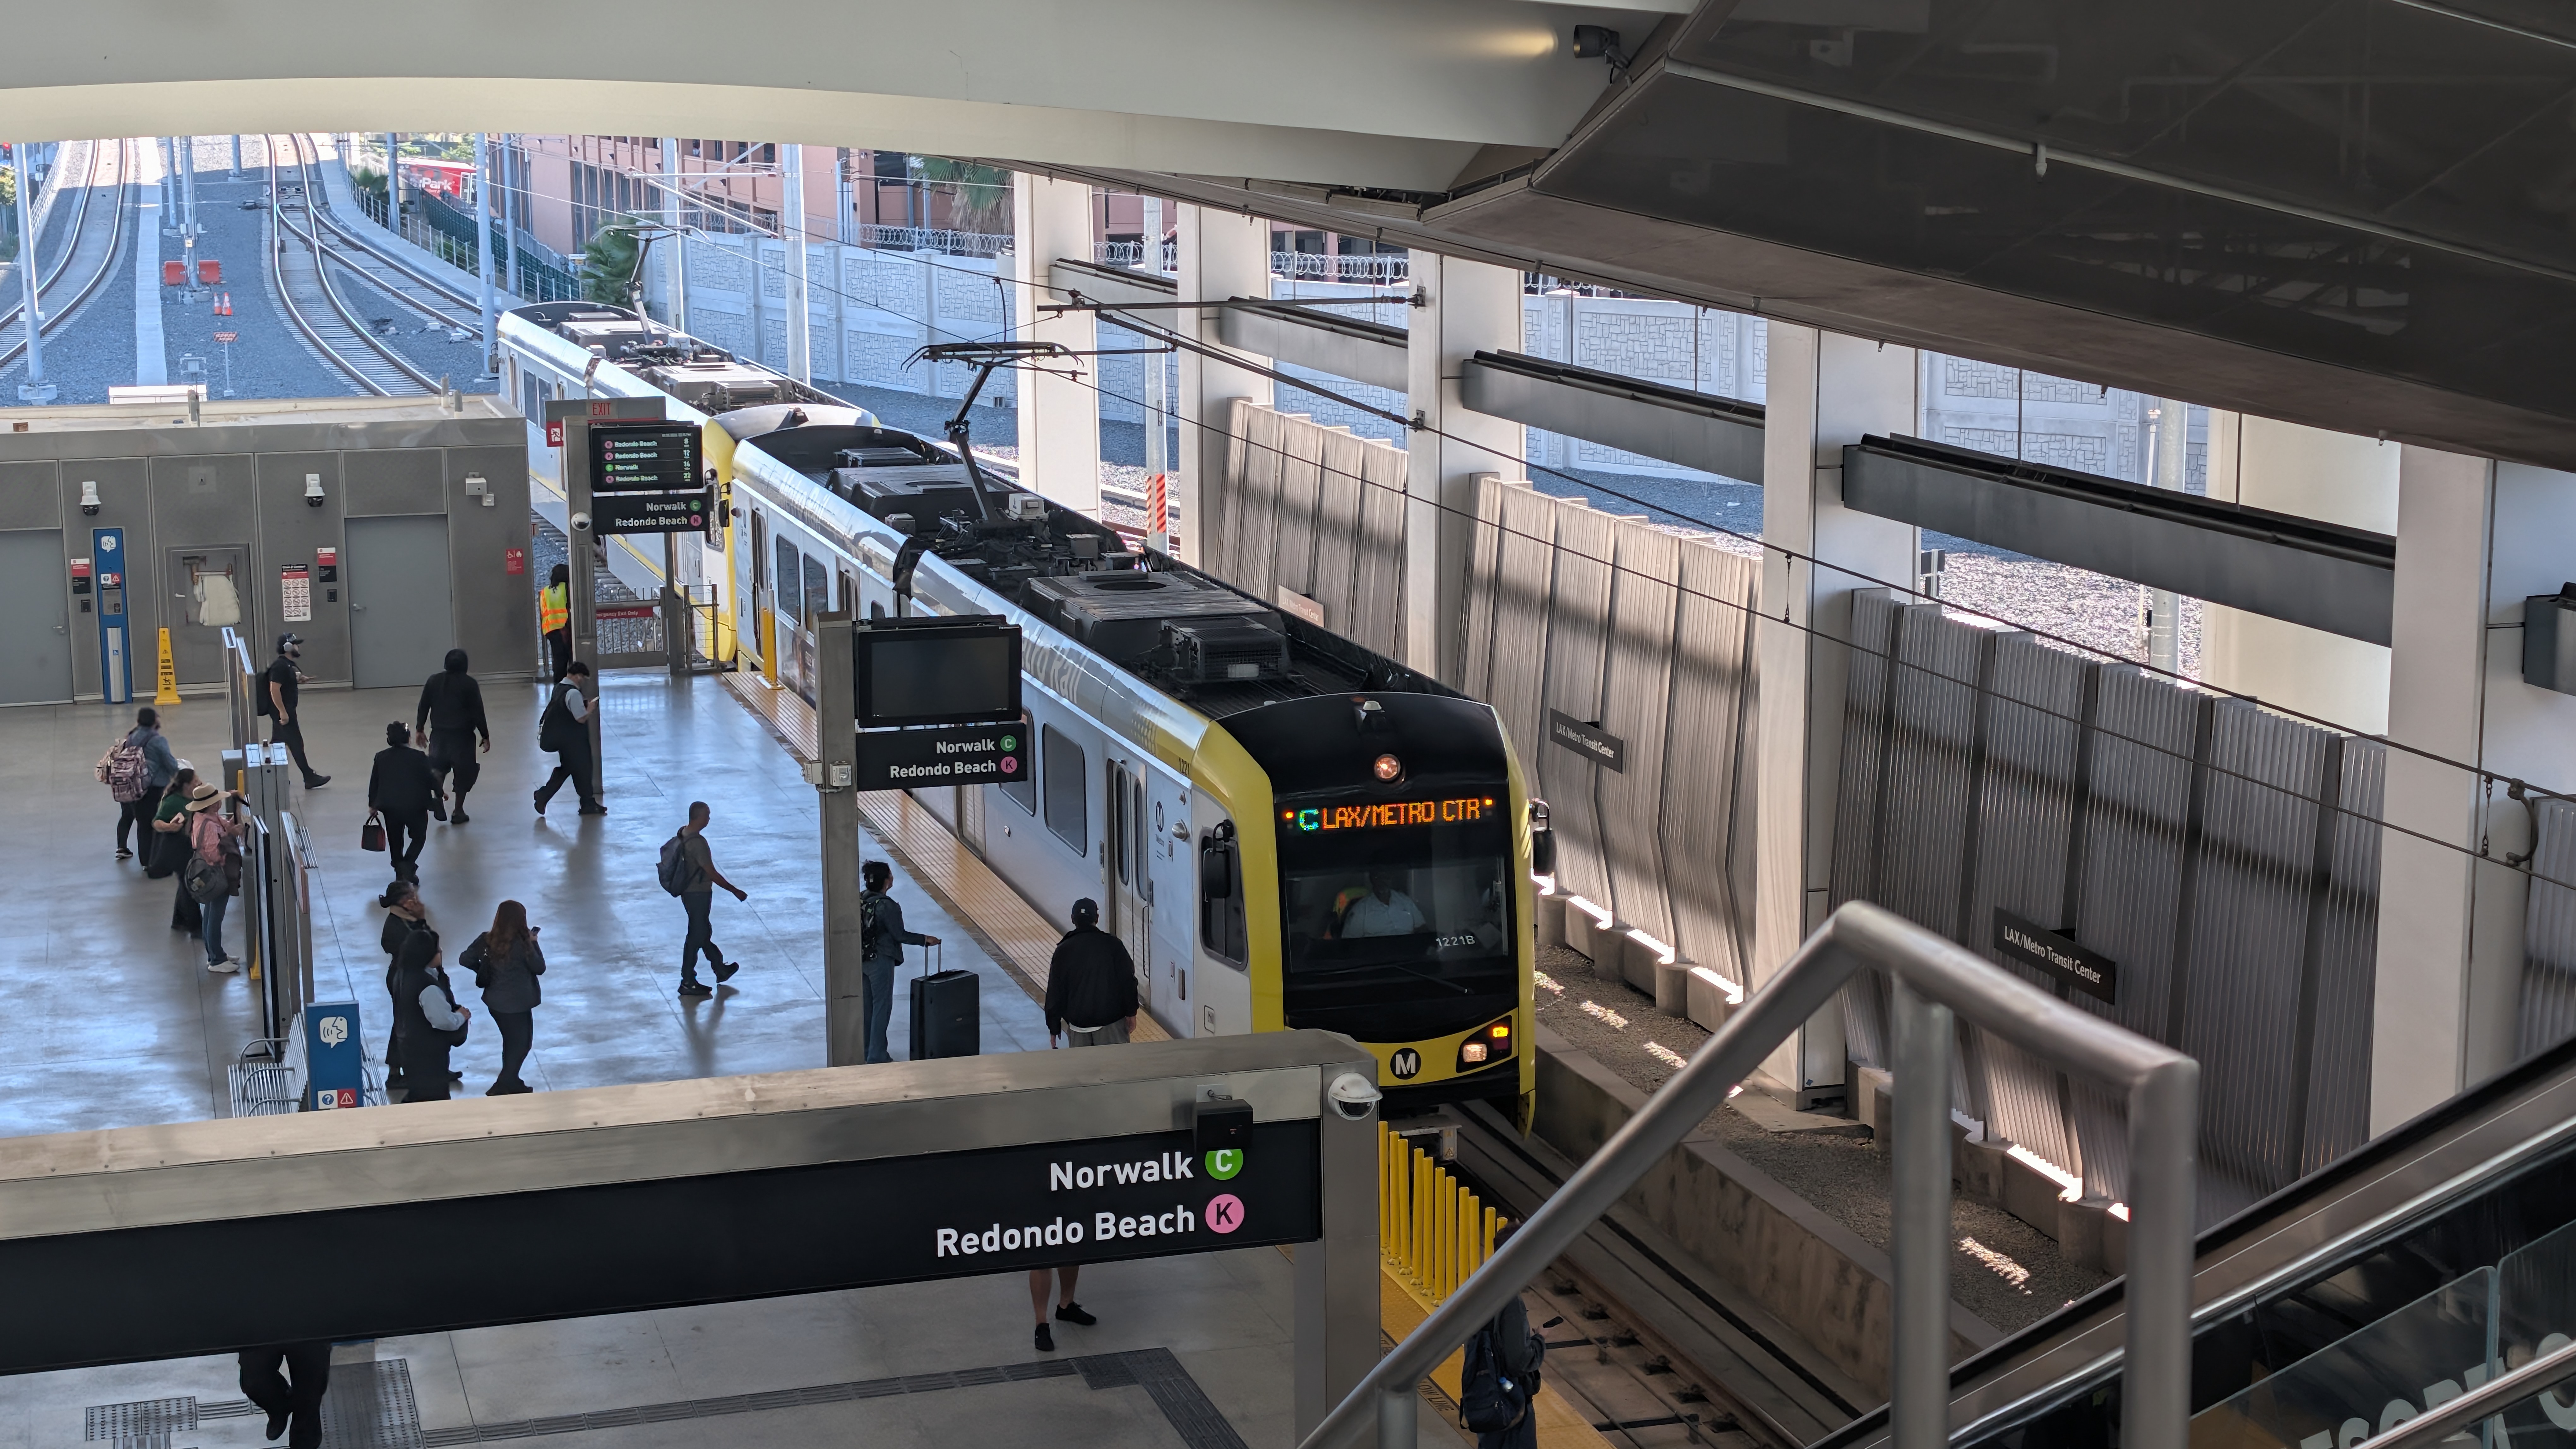 Photo by Samuel Sharp / BuildSD
State Formula Funds (TDA)
The State of California also provides significant funding to local transit agencies. The Transportation Development Act (TDA) governs most transit funding in California. TDA includes two major funding programs. Local Transportation Fund (LTF) comes from the state sales tax, returned to the county of origin, and State Transit Assistance (STA) comes from the state sales tax on diesel fuel.
LTF: Local Transportation Fund
The LTF is the first major formula fund for public transit. It comes from one quarter-cent of California’s state sales tax. LTF funding levels vary by county based on economic activity because it is tied to the local sales tax. LTF money can be spent on transit operations and planning, and is awarded via return to the county of origin. Each county’s Regional Transportation Planning Agency (RTPA, e.g. SANDAG or LA Metro) distributes LTF funds amongst their transit operators. This leads to large disparities in funding for different RTPAs and transit agencies.
LTF funds can also be spent on roads in counties with populations under 400,000, but only if there are no unmet transit needs. An Unmet Transit Needs Process must be conducted annually by regional transportation planning agencies. This requires the agency to determine whether there are “unmet transit needs that are reasonable to meet” before LTF funds can be spent on streets and roads. Unmet needs only apply for existing transit services or service variants that are not adequately meeting the identified transportation needs. Operational improvements don’t count, and there has to be community interest, potential ridership, and sufficient LTF funding available for the need to be “reasonable to meet.” We could write another article about the Unmet Transit Needs Process alone, but we’ll leave it at this for now.
STA: State Transit Assistance
The STA is the other major transit source of state formula funds. STA money comes from the California Public Transportation Account. Of that tax, a rate equal to 7.625% of the diesel sales price goes to STA: 4.125% from the base program and 3.5% from the increase under SB 1 (2017-2018). It also receives transfers from the State Transportation Fund. STA money is split into population-based and revenue-based funds. Half of the funds go to each RTPA based on population. The other half goes to each operator based on its qualifying local revenue, such as fares and local taxes.
STA money can be spent on both transit operations and capital projects. Some uses for the funds include transportation planning, Intercity Rail programs, and the State Transportation Improvement Program (STIP). The Road Repair and Accountability Act of 2017 (SB 1) increased STA’s allocation and introduced the State of Good Repair Program (SGR) as one use for STA funds. SGR funds for Fiscal Year (FY) 2019-20 through FY 2025-26 could be redirected to address funding shortfalls in operating or capital expenses resulting from the impact of the COVID-19 pandemic.
Excise taxes on gasoline and diesel vary by jurisdiction. California has the largest diesel and gasoline tax of any state in the nation. As with federal formula funds which come from the Mass Transit Account, the California Public Transportation Account also faces longer-term declines as EV adoption and fuel efficiency will reduce diesel sales tax revenues over time. And because STA comes from the sales tax on diesel fuel instead of an excise tax, it is also vulnerable to economic changes over time. To address this, STA also receives funds from the State Transportation Fund, which comes from registration fees based on the value of the vehicle. This will insulate the STA from most impacts, but it will need to be amended as diesel fuels are phased out over time.
Competitive and Discretionary Project Grants (Federal and State)
In addition to formula grants, project grants are another kind of funding awarded to transit. Grants can be awarded on a competitive or discretionary basis. Grants are money that agencies do not need to pay back in most circumstances.2
Funding through competitive and discretionary grants are awarded by application. Applicants submit proposals that the awarding agency evaluates against published criteria, such as project merit and cost-effectiveness. Only the highest-ranked proposals receive funding. Therefore, grant funding awards are not guaranteed, however, they are an important tool transit agencies use to meet their capital and operating needs.
Capital Investment Grants (CIG, section 5309) are the primary federal program for new fixed-guideway projects. CIG grants fund new and expanded fixed-guideway projects, including heavy rail, light rail, commuter rail, streetcar, and bus rapid transit. Other grants fund Low or No Emissions projects or replacement buses. At the state level, competitive grants include the Transit and Intercity Rail Capital Program (TIRCP) and the Low Carbon Transit Operations Program (LCTOP).
Most project grants require matching funds, especially for capital projects. In general, the FTA grants funding for 80% of capital projects, meaning Capital Investment Grants require a 20% local match. Some “earmark” grants are enacted in appropriations for specific purposes. These bypass the usual competitive selection process and are awarded directly to local agencies. Project grants also fund experimental or pilot transit services, however, grants can’t be relied on as a long term funding source because they will expire.
 Photo by Samuel Sharp / BuildSD
Local Special Taxes and Bonds
Local areas supplement state- or federal-level funding with special taxes or bonds. The purpose and scope of these funds vary by jurisdiction. The great advantage of local funding measures is their flexibility to be allocated for the needs of the local region.
Special Taxes
Local governments, including transit agencies, can also be enabled to raise taxes. The two main kinds of taxes available to transit agencies are sales taxes and special assessments. All new local taxes in California are subject to voter approval. While general-purpose sales taxes can be passed with a majority vote, under Propositions 13 (1978) and 218 (1996), special-purpose taxes proposed by any government or special district require a two-thirds threshold to be passed. This means a minority of voters can reject a new or increased tax, even if a clear (but not two-thirds) majority supports it. Courts have held that citizen-initiated special taxes are not subject to the two-thirds threshold.3
Sales tax
Sales taxes are charged at the point of purchase. In California, the state sales tax is 7.250% — 7.25 cents per dollar4 — but the actual sales tax varies widely by jurisdiction as cities, counties, and special tax districts can levy their own sales taxes. Some of that sales tax already goes to transit. For example, one quarter-cent goes to the LTF. However, local governments and transit agencies are empowered to propose additional sales taxes for special purposes, including transit funding. New taxes can also be proposed by citizen’s initiative.
In San Diego County, the base sales tax rate is 7.750% because voters approved the half-cent TransNet tax. TransNet is an example of how local sales taxes can be put to work for transit. In addition to paying for various road projects, TransNet funds transit capital projects like Rapid bus routes and the Mid-Coast Extension of the UC San Diego Blue Line Trolley, as well as operations for these projects.
The San Francisco Bay Area is currently considering the Regional Transit Measure (Proposition RTM, 2026), which will levy a half-cent sales tax on a five-county area (one cent in San Francisco) with the money being distributed towards operational funds for the regional operators in the area, including BART, Muni, Caltrain, and AC Transit, among others.
Opponents of sales tax often criticize the regressive nature of sales taxes, since they are a flat rate assessed on purchases. Therefore, lower-income consumers pay a higher portion of their incomes in taxes. Like federal and state funds derived from sales taxes, local sales taxes are also subject to economic volatility, and make less money during recessions as purchasing goes down. These are the times when transit is needed the most.
Parcel tax
Parcel taxes are another kind of special tax assessed on units of real property (i.e. pieces of land). These are distinct from ad valorem property taxes, which are assessed based on the assessed value5 of the property. Parcel taxes are not based on the value of the property. Instead, they generally assess the same fixed-dollar amount to every parcel, regardless of its size or use, or the benefit it receives from the service it funds. Parcel taxes are not subject to Proposition 13, which limits the assessed value of real estate, because they do not vary with the assessed value of the property.
Flat-rate parcel taxes are simple to administer; however, they are a regressive tax because all property owners pay the same rate regardless of the value of the property. Flat-rate parcel taxes also assume the benefit of the property tax is roughly equal for each parcel, which may not necessarily be true for a transit service where some types of parcels may benefit more from transit than another (e.g. a commercial parcel on a busy urban corridor benefits much more from transit than a vacant parcel in the suburbs).
Because of this, variable rate parcel taxes are becoming increasingly common. These have been especially prominent in the San Francisco Bay Area, with several taxes approved in 2024. Proposition H (2026) would levy a tax to support Muni’s operating deficit. Most single-family parcels would pay $129, but an additional tax of $0.42 per square foot of building area between 3,001 and 5,000 square feet (and $1.99/square foot above 5,000 square feet) accounts for the varying value of parcels (and benefit of Muni to them) without being subject to the restrictions on ad valorem property taxes under Proposition 13. Similarly, multi-family, non-residential, and vacant parcels are subject to different rate structures. As a citizen’s initiative, Proposition H requires a simple majority to pass.
 Photo by Grey Crawford / BuildSD
Bonds
Bonds are money local governments can borrow. Bonds usually are used to fund one-time capital needs, as using debt to fund operating costs is unsustainable in the long term. A bond is a security sold by the government and paid back over time, with interest. This gives local governments and transit agencies upfront cash to finance longer-term capital expenditures.
General Obligation (GO) Bonds are typically subject to voter approval and are most common for transit agencies with authority to levy property taxes to pay them off. At the state level, Proposition 1A (2008) authorized the sale of $9.95 billion worth of statewide General Obligation bonds to the California High-Speed Rail Authority. At the regional level, Measure RR (2016) authorized $3.5 billion in bond funding for infrastructure and other capital improvements for Bay Area Rapid Transit (BART). GO Bonds are also common for school-related bonds, as the San Diego Unified School District is attempting this year with Measure M.
Revenue Bonds are the dominant kind of bond for transit agencies. They are repaid through either dedicated sales taxes (e.g. Measure M, 2016) or through system revenue (e.g. farebox). Revenue Bonds themselves do not require separate voter approval (although any taxes to fund them still do). They work well because agencies often have dedicated funding streams they can use to back the bond.
The biggest advantage of bonds is upfront funding. Bonds are commonly used for school improvements and other projects where funds are needed before tax revenues arrive. This avoids the difficult challenge of raising taxes quickly. Bonds are also stable and low-risk for investors, and they spread the cost of long-term investments across the generations that benefit from them. In the world of public transit, bonds are used for large, long-lived capital investments like rail fleet investments, construction of new rail lines, and infrastructure rehabilitation and modernization.
However, bonds raise drawbacks tied to interest rates. Higher rates raise the cost of borrowing money and refinancing mature debt. Interest payments also consume future budgets and servicing this debt shifts costs to future taxpayers, who have to repay bonds for projects they may not have chosen.
 Photo by Samuel Sharp / BuildSD
Fares
Fares are the last major source of funding for public transit. They are the price riders pay to use public transit service. However, they are a limited source of funding. Farebox recovery, the amount of money transit agencies cover using fares, is typically well below 50% for US transit agencies, although this varies substantially from agency to agency. Fares also cost money to collect and enforce. Fares are kept low by design. Transit is a public service, and higher fares reduce ridership and burden low-income riders, who make up much of the rider base. Raising fares also has diminishing returns, because each increase can drive away riders and offset the added revenue per trip.
Most operating expenses, such as fuel, driver salaries, and maintenance costs are fixed or mostly fixed regardless of ridership. If transit had to fund itself entirely with fares, they would have to be increased substantially, which reduces ridership further and forces additional increases or service cuts, creating a “death spiral.” This creates strong equity considerations and would make transit much less effective over time. Low-ridership routes would be cut first, since they recover the least from fares. Low-income riders, who make up much of transit’s rider base, would be hit hardest, losing affordable access to opportunity. Finally, capital investments would stall as system expansion would be unaffordable without grants or bonds.
Therefore, fares cannot fund public transit on their own. Agencies depend on stable funding from Federal and State governments, or taxes and bonds, to fund stable operations.
 Photo by Grey Crawford / BuildSD
Why does San Diego public transit need more operating funding?
In San Diego, the threat to transit funding is not abstract. Nearly half of MTS’s operating funding comes from Federal and State formula funds – 47.8% of the budget in 2024. Yet, costs have risen dramatically and budgets grow year-over-year. Ridership is starting to recover from the pandemic, but it hasn’t quite recovered yet, and even so, fares are only a small part of the budget. MTS has balanced its budget from stimulus funds, but these funds are running out soon. MTS has also seen weak TransNet tax revenue. Even so, fuel efficiency, EV adoption, economic conditions, and federal authorization all pose threats to the federal and state formula funds MTS needs to sustain service. In short, MTS’s recurring revenues do not cover recurring expenses. When pandemic relief funds run out, MTS faces the “fiscal cliff.” When that happens, San Diego voters will be faced with a difficult choice - fund transit directly, or face steep service cuts.
Footnotes
-
1 - The Mass Transit Account gets its revenue from a piece of the Gasoline (2.86 cents out of 18.4 cents per gallon) and diesel (2.86 cents out of 24.4 cents per gallon) federal excise tax. The remaining federal gas tax goes to the Highway Account (roads/bridges). ↩
-
2 - Early disposal of assets is the most common agencies need to pay back grants. FTA rules require buses purchased with federal funds to be used for their maximum useful life (12 years for a standard bus). If an agency retires a bus early, they’d have to reimburse the FTA’s share of the asset’s remaining value. Grants can also be returned in cases of failing to complete a project by a deadline. ↩
-
3 - Proposition 43 (2026) would require two-thirds for voter-proposed local special taxes starting Jan. 1, 2027. ↩
-
4 - The base sales tax in California is made up of a 6% state tax, and a 1.25% tax allocated to cities and counties. ↩
-
5 - In California, the assessed value of real property is based on Proposition 13, also called the People's Initiative to Limit Property Taxation. It limits the rate of taxation to 1% of the parcel’s assessed value and limits the annual increase of that assessed value to the lesser of CPI or 2% per year, starting at the 1975-76 value, or the date of sale of the property. Therefore, the assessed value of real property can be much less than the property’s actual value. Property is reassessed whenever a change in ownership occurs. ↩